Some of the links below are affiliate links: if you buy through them we may earn a small commission at no extra cost to you. As an Amazon Associate I earn from qualifying purchases. We only suggest things we would recommend to a friend — see our affiliate disclosure and how we research.
✉ Join the Dispatch — a calm weekly note, every Thursday. Free.
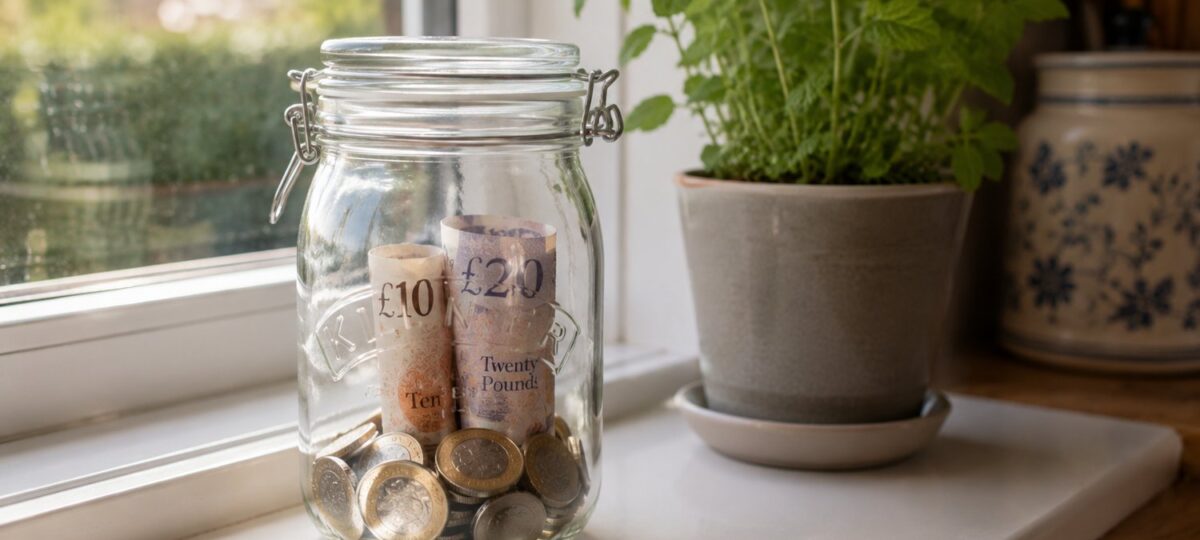
Most people know roughly what a budget is. Fewer know about sinking funds — and that’s a shame, because they’re one of the most practical tools for managing money when you know big expenses are coming but don’t quite know how to plan for them.
A sinking fund isn’t complicated. It’s just a dedicated pot of money you build up slowly so that when a large, predictable expense arrives, you already have what you need. No scrambling, no credit card, no stress.
What a sinking fund actually is
The term comes from accounting — specifically the idea of “sinking” a debt by making regular contributions toward it over time. In personal finance, it’s been adapted to mean any dedicated savings pot set aside for a specific, anticipated expense.
The key word is anticipated. A sinking fund is not for emergencies (that’s your emergency fund). It’s for things you know are coming — car insurance renewal, Christmas, a summer holiday, a new boiler that’s living on borrowed time, school uniform season. These aren’t surprises. They just feel like it when they land because there’s no money waiting for them.
With a sinking fund, you spread the cost over the months leading up to the expense. Instead of finding £600 for car insurance in October, you put £50 away every month. By the time the bill lands, the money is already there.
How sinking funds differ from an emergency fund
It’s worth being clear on the distinction because conflating them is one of the most common ways both funds get quietly drained.
Your emergency fund is for genuinely unexpected, unavoidable costs — a boiler that breaks without warning, an urgent dental appointment, a sudden job loss. You don’t know when these will happen or how much they’ll cost. The fund exists to absorb shock.
Your sinking funds are for costs you can see coming. The annual timing is known. The approximate amount is known. You’re just choosing to save for them in advance rather than panic when they arrive.
Keep them genuinely separate — ideally in different pots or accounts. If your emergency fund keeps getting used for car insurance, it’s not doing its job.
Which expenses work best as sinking funds
Almost any irregular but predictable expense is a sinking fund candidate. In the UK, the most useful ones tend to be:
- Car insurance and road tax — often annual lump sums that feel enormous if you haven’t saved toward them
- Christmas — arrives every year on the same date, somehow still catches people out. A £600 Christmas costs £50/month saved from January
- Holidays — whether a week abroad or a UK break, saving monthly makes the booking feel affordable rather than extravagant
- Home maintenance — a general pot for things like redecorating, a new appliance, or garden work
- School costs — uniforms, trips, PE kits, and the various surprise contributions that come home in book bags
- MOT and car servicing — these happen on a schedule; saving monthly removes the annual dread
- Birthdays and gifts — if you have a lot of family birthdays clustered together, a small monthly gift fund prevents a horrible month
You don’t need a sinking fund for everything. Start with the two or three expenses that most reliably cause you stress when they appear, and build from there.
How to set one up in practice
The mechanics are simple. For each sinking fund:
- Name the expense and estimate the total cost (e.g. “Christmas — £500”)
- Work out the monthly contribution by dividing the total by the number of months until you need it (e.g. £500 ÷ 10 months = £50/month)
- Open a separate account or pot for it — most modern UK banks (Monzo, Starling, Chase, Nationwide Flex) allow multiple savings pots with individual labels
- Set up a standing order to move the monthly amount in on payday, before you have a chance to spend it elsewhere
That’s genuinely it. The magic is in the automation and the separation. When the expense arrives, you transfer from the pot. You don’t have to think, stress, or reach for credit.
Where to keep sinking funds in the UK
You have a few practical options depending on how many funds you want to run:
Savings pots within your bank app — Monzo, Starling, and Chase all let you create named pots within your account. These earn modest interest and are very easy to manage. Good for most people running 3–6 sinking funds simultaneously.
A dedicated easy-access savings account — if you only have one or two larger sinking funds (e.g. a holiday fund and a home maintenance pot), a separate easy-access savings account earning 4–5% AER works well. Marcus, Chip, and Atom Bank offer competitive rates.
A cash ISA — for a larger sinking fund you won’t touch for 12+ months (like a new car fund), a cash ISA keeps your interest tax-free. Just make sure it allows withdrawals when you need them. If you want a simple way to see all your pots in one place, Emma connects to your bank accounts via open banking and shows your balances and spending at a glance — handy when you’re running several sinking funds across different apps or pots.
The golden rule: wherever you keep them, they must be separate from your current account. If they’re mixed in with your everyday money, they’ll disappear.
Common questions about sinking funds
What if I can’t afford to fund everything at once? Start with one or two. Pick the expenses that hit hardest or most frequently. You don’t need a perfect system from day one — one funded sinking fund is infinitely better than none.
What if the expense turns out to be more than I saved? Top it up from your general budget and adjust your monthly contribution going forward. No sinking fund is ever perfect on the first pass.
Should I use a sinking fund or a 0% credit card? A sinking fund is almost always better — you own the money, there’s no risk of missed payments, and there’s no stress about clearing the balance before the promotional period ends. The credit card approach only makes sense if you earn rewards and pay it off instantly.
Why they work when regular budgeting doesn’t
One of the reasons sinking funds are so effective is that they make big, irregular costs feel manageable. Instead of facing a £600 bill, you’re making a £50 monthly decision — which is much easier to say yes to. They pair particularly well with a clear budgeting framework; the 50/30/20 budget rule is a useful starting point for working out how much you can realistically set aside each month.
They also remove decision fatigue. Once the standing order is in place, you don’t need to decide whether to save for Christmas each month. It just happens. And when the festive season arrives, you can buy presents with money you’ve already set aside, rather than putting it on a card and regretting it in January.
Start with Christmas or car insurance — whichever is the most reliable source of financial stress in your year. Open a pot, name it, set the standing order. That’s all it takes to stop dreading the same expenses every single year.
💰 From the D&L Shop: Ready to take control of your household budget? Our Household Budget Reset is a 5-page printable workbook covering income, outgoings, spending, and savings goals — £3.99. Also free: the Weekly Budget Meal Planner to cut your food bill. Browse the full shop →
🛡 Our standards: How we research · Editorial policy · Affiliate disclosure · Corrections · Last reviewed: April 2026
About Gareth
Gareth Isherwood is the editor of Danbury & Lovejoy. He has baked bread at home for 25+ years and has 15 years of growing experience across gardens, containers and other growing spaces, including an East Sussex allotment for the past three years. Read his full story →
Was this useful?